Application of an Enhanced Longformer Model for Cross-Cycle Power Trading Trend Forecastin
DOI:
https://doi.org/10.64972/dea.2024.v3i1.4342d:17-29Keywords:
Longformer, Power Trading, Cross-cycle Forecasting, Sparse Attention, Residual Trend PredictionAbstract
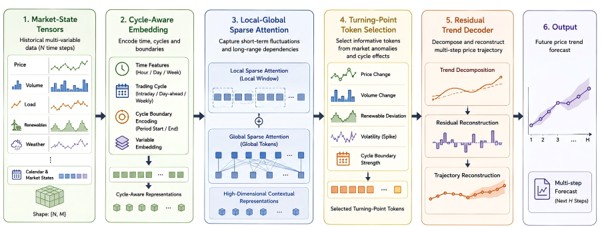
Cross-cycle power trading trend forecasting requires models capable of representing long historical sequences, heterogeneous market variables, cycle-dependent temporal patterns, and abnormal market-state transitions. Existing statistical models have limited nonlinear representation, recurrent networks compress long histories into hidden states, and dense Transformer attention is computationally expensive for extended hourly trading records. This paper proposes an enhanced Longformer model for cross-cycle electricity trading trend forecasting. The method constructs a cycle-aware market state tensor from price, transaction volume, load, renewable generation, weather variables, calendar labels, and market-state indicators. A cycle-coupled local-global sparse attention module is designed to combine short-range volatility tracking with long-range interaction among intra-day, day-ahead, weekly, and medium-term trading cycles. Turning-point tokens are selected from price movement, volume movement, renewable deviation, volatility, and cycle-boundary intensity. A residual trend decoder reconstructs multi-step price trajectories from incremental market movements and is optimized by residual fitting, direction consistency, and volatility plausibility. Experimental results on an 18-month hourly dataset show that the proposed model achieves MAE 18.42 CNY/MWh, RMSE 27.86 CNY/MWh, MAPE 3.91%, and directional accuracy 84.7% in 48-step forecasting, outperforming ARIMA, SVR, LSTM, GRU, Transformer, Informer, and Autoformer. The results indicate that cycle-aware representation, turning-point token selection, and residual decoding jointly improve forecasting accuracy, horizon stability, and inference efficiency for intelligent power trading systems.
Downloads
Published
How to Cite
Issue
Section
License
Copyright (c) 2024 Chia-wei Keng, Pei-ming Yen, Chia-chun Mai

This work is licensed under a Creative Commons Attribution-NonCommercial-ShareAlike 4.0 International License.